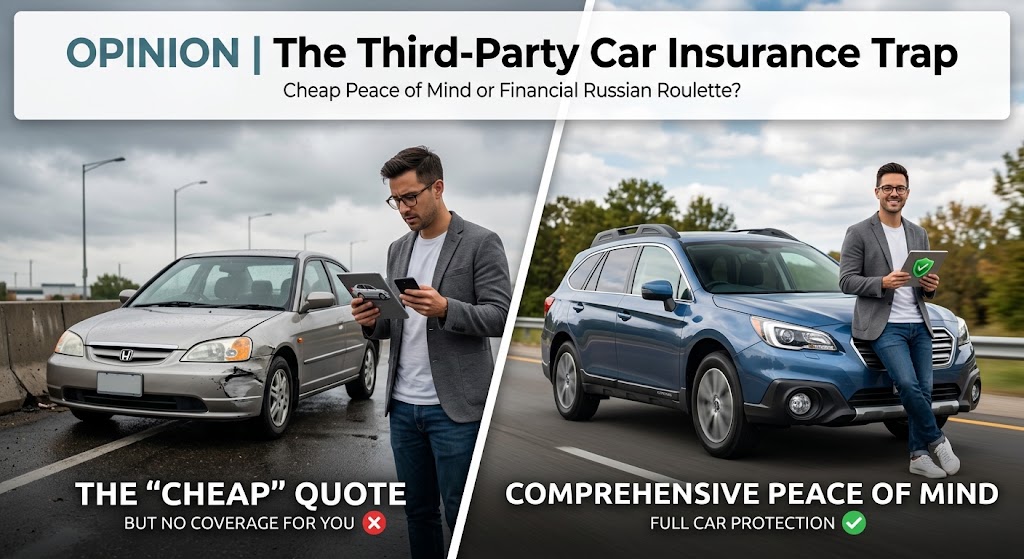
Let’s be honest for a second: nobody wakes up excited to shop for car insurance. We open our browsers, head to a comparison site, and within three minutes, our eyes land on the absolute cheapest number on the screen: Third-Party Coverage.
It looks like an absolute steal, especially compared to the eye-watering price tag of a full comprehensive policy. But before you click "buy" and congratulate yourself on outsmarting the system, we need to have a quick real-talk session about what that quote actually buys you—and what it leaves out on the asphalt.
What Your Third-Party Quote Actually Means
Here’s the baseline truth: a third-party policy is designed to protect everyone else’s wallet except yours.
If you cause an accident, third-party liability steps in to pay for:
-
Property Damage: The bumper of that pristine SUV you accidentally rearended.
-
Bodily Injury or Death: Medical bills or legal liabilities for passengers, pedestrians, or other drivers involved.
In short? It stops you from getting sued into oblivion by someone else. That’s vital, and it’s why basic liability is legally mandatory in most places.
The Uncomfortable Catch (Read Before Buying!)
Here’s where the budget-friendly high wears off. You hit a slick patch of road, skid into a concrete divider, and wreck your front axle. You get home, call your insurer, and realize: You get zero dollars.
| What's Covered? | Third-Party Only | Comprehensive Policy |
| Damage to other vehicles | ✅ Yes | ✅ Yes |
| Third-party medical bills | ✅ Yes | ✅ Yes |
| Damage to YOUR car | ❌ No | ✅ Yes |
| Theft or Carjacking | ❌ No | ✅ Yes |
| Natural Disasters / Flood | ❌ No | ✅ Optional / Add-on |
If your car is stolen out of your driveway, catches fire, or gets totaled in a single-car incident, a third-party policy leaves you holding 100% of the bill.
Is a Third-Party Quote Right for You?
I’m not saying third-party quotes are a total scam. They serve a very specific purpose.
Go for Third-Party if:
-
Your car is old, fully paid off, and its total market value is barely higher than your annual insurance deductible.
-
You have cash saved up to outright replace or repair your car tomorrow if disaster strikes.
-
The car rarely leaves the garage and is driven minimal miles a year.
Avoid it if:
-
You are financing or leasing the vehicle (your lender won't allow it anyway).
-
Your car is your primary asset and losing it would ruin your daily commute or livelihood.
-
You live in an area prone to severe weather or high theft rates.
My Blogger Verdict: Don't Quote in a Vacuum
Before you lock in that low monthly premium, do yourself a favor: run a quick comparison for Third-Party, Fire & Theft or a mid-tier Comprehensive policy. Sometimes the price difference is as little as a couple of iced lattes a month—and that tiny gap could be the only thing standing between a minor headache and total financial heartbreak.
Drive safe, read the fine print, and never shop quotes when you're in a rush!